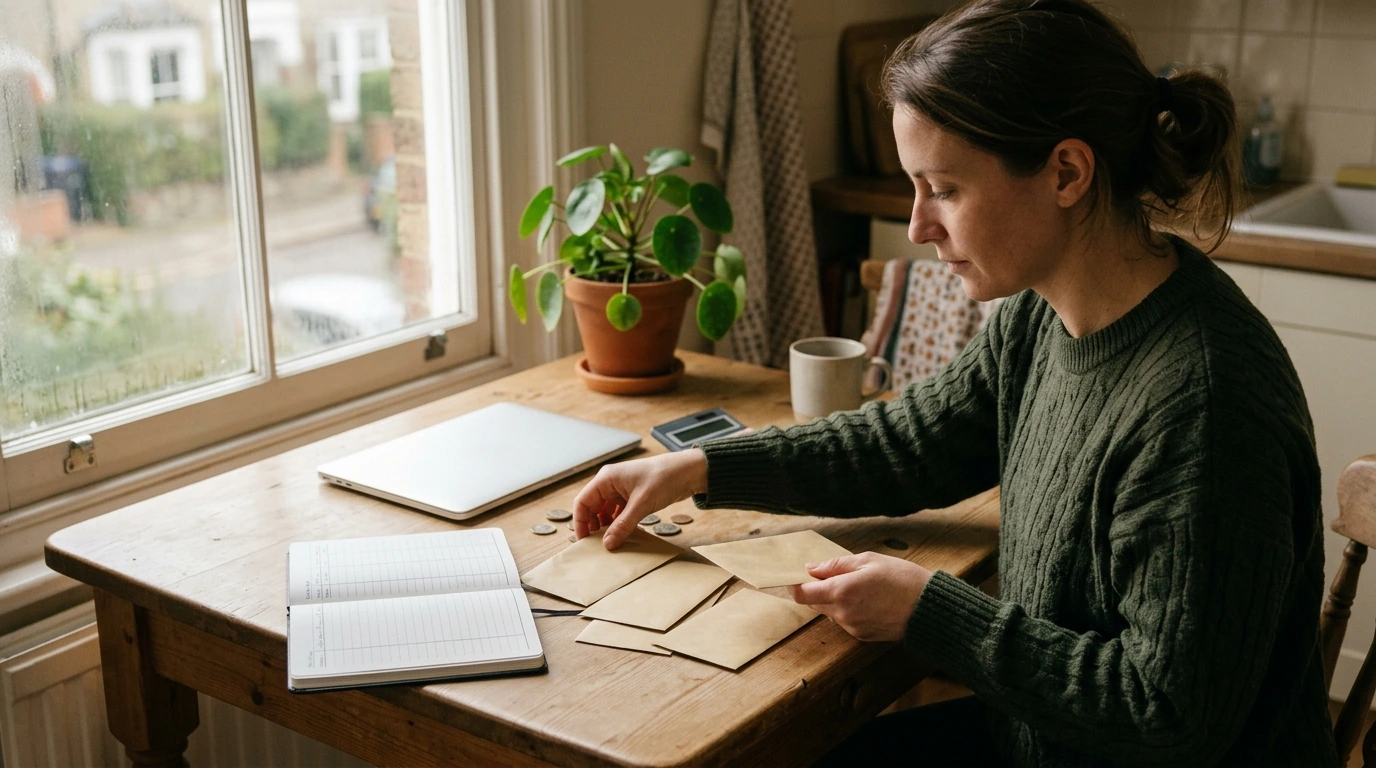
A $4,000 monthly income can feel either tight or empowering depending on how the money is assigned before the month begins. A smart budget is less about restriction and more about clarity: covering essentials, staying ahead of bills, building savings, and still leaving room for real life. This guide lays out a practical monthly blueprint—how to set up categories, choose a method that fits your habits, and handle common curveballs—so the plan works on a normal month, not just an ideal one.
Start with the numbers that matter (the “true” monthly picture)
Before choosing categories, get a clean baseline. Use take-home pay (after taxes and benefits) and count only income you can reliably expect. If you’re paid biweekly or receive variable commissions, translate it into a conservative monthly number so you don’t budget money that isn’t there yet.
Lock in fixed obligations first
List what must be paid no matter what: rent/mortgage, minimum debt payments, insurance premiums, subscriptions you truly keep, childcare, and any non-negotiable support obligations. These are the “keep the lights on” items that your plan must protect.
Turn irregular expenses into monthly sinking funds
Most budgets break from “random” expenses that aren’t random at all—car maintenance, medical co-pays, annual fees, gifts, travel, back-to-school, and home repairs. Decide what you’ll set aside each month so those costs land softly when they arrive.
Choose a budgeting calendar you’ll actually follow
Decide whether your budget resets on the 1st or runs payday-to-payday. Align bill due dates with paychecks when possible, set reminders, and pick a consistent weekly check-in day. If fixed costs plus minimums exceed roughly 70–75% of income, focus first on trimming commitments or renegotiating bills before trying to perfect every category.
Pick a system that fits how money actually gets spent
The “best” budget method is the one that matches your spending patterns and attention span.
Zero-based budgeting
Every dollar gets a job—bills, savings, debt, and fun—until you hit zero. This is great for reducing “mystery money” and building faster momentum.
50/30/20-style framework
This ratio method (needs/wants/savings & debt) creates quick structure without micromanaging. It’s useful if your expenses are fairly steady and you mainly need guardrails.
Cash stuffing or envelope categories (digital or physical)
A practical hybrid for $4,000 months
A realistic $4,000 monthly budget blueprint (example allocations)
Sample $4,000 Monthly Budget (Starting Point)
| Category |
Target ($) |
Notes |
| Housing (rent/mortgage + basic utilities) |
1400 |
Adjust to local costs; include electricity/water/trash if consistent |
| Groceries + household supplies |
450 |
Separate from dining out to keep the signal clear |
| Transportation (fuel/transit/maintenance sinking fund) |
400 |
Include insurance here only if paid monthly; otherwise place in Insurance |
| Insurance (health/auto/renters/life) |
300 |
If payroll-deducted, use actual out-of-pocket portion |
| Debt minimums (credit cards/loans) |
350 |
Minimums only; extra payoff gets its own line item |
| Savings (emergency fund + sinking funds) |
450 |
Prioritize a starter buffer, then build toward 3–6 months |
| Discretionary (dining, fun, personal, subscriptions) |
400 |
Cap it; move unused amounts to goals at month-end |
| Extras: goals (extra debt payoff / investing / big goal) |
250 |
Direct toward the highest-impact goal for the season |
Make the budget stick: setup, automation, and guardrails
Create a bills buffer so timing stops causing stress
Automate the essentials right after payday
Use category caps where leaks usually happen
For more guidance, a structured planner can help you repeat the routine month after month: Master Your $4,000: The Smart Monthly Budget Blueprint for Financial Freedom (Digital Budgeting eBook).
Handling common $4,000-month challenges without quitting the plan
Irregular income
High rent
Debt pressure
Unexpected expenses
Overspending cycles
Turn a monthly plan into financial freedom milestones
Milestone 1: One-month buffer
Milestone 2: Starter emergency fund
Milestone 3: Debt reduction phase
Milestone 4: Long-term growth
For motivation, it helps to keep a small, planned “treat” inside your discretionary cap rather than breaking the budget impulsively. If you’re budgeting personal accessories, a modest option like the hand-crocheted cotton triangle scarf headband can fit as a pre-planned purchase. If pet care is part of your monthly life admin, planning for tools like the LED illuminated pet nail clipper with anti-splash guard can also reduce “surprise” spending later.
A guided option for planning your month (digital budgeting eBook)
If you want a step-by-step way to plan a $4,000 month—categories, allocations, and a repeatable routine—use a guided blueprint designed around this income level. It’s especially helpful if you want fewer money surprises and a system you can reuse without starting over each month: Master Your $4,000: The Smart Monthly Budget Blueprint for Financial Freedom (Digital Budgeting eBook).
For additional budgeting basics and consumer-focused tools, visit the Consumer Financial Protection Bureau budgeting resources and the Federal Trade Commission guide to making a budget.
FAQ
How much should be saved each month on a $4,000 income?
A practical target is often 10%–20% ($400–$800), but the right number depends on rent and debt minimums. Start with a starter emergency fund and core sinking funds, then increase savings and investing once you’ve stabilized bills and reduced high-interest debt.
Is $4,000 a month enough to live comfortably?
It can be, but comfort depends heavily on housing costs, debt, and household size. A simple test is whether fixed costs and minimum payments stay under about 70–75% of take-home pay; if they don’t, focus on lowering the biggest fixed expense or increasing income.
What’s the simplest way to budget monthly without tracking every receipt?
Automate fixed bills and savings, then set firm caps for 2–4 variable categories like dining, groceries, and shopping. Do a quick weekly check-in to confirm balances and upcoming due dates, using separate accounts or digital “envelopes” to keep limits clear.
Recommended for you



Leave a comment