Budgeting Like a Pro: Plan Spending, Debt and Savings
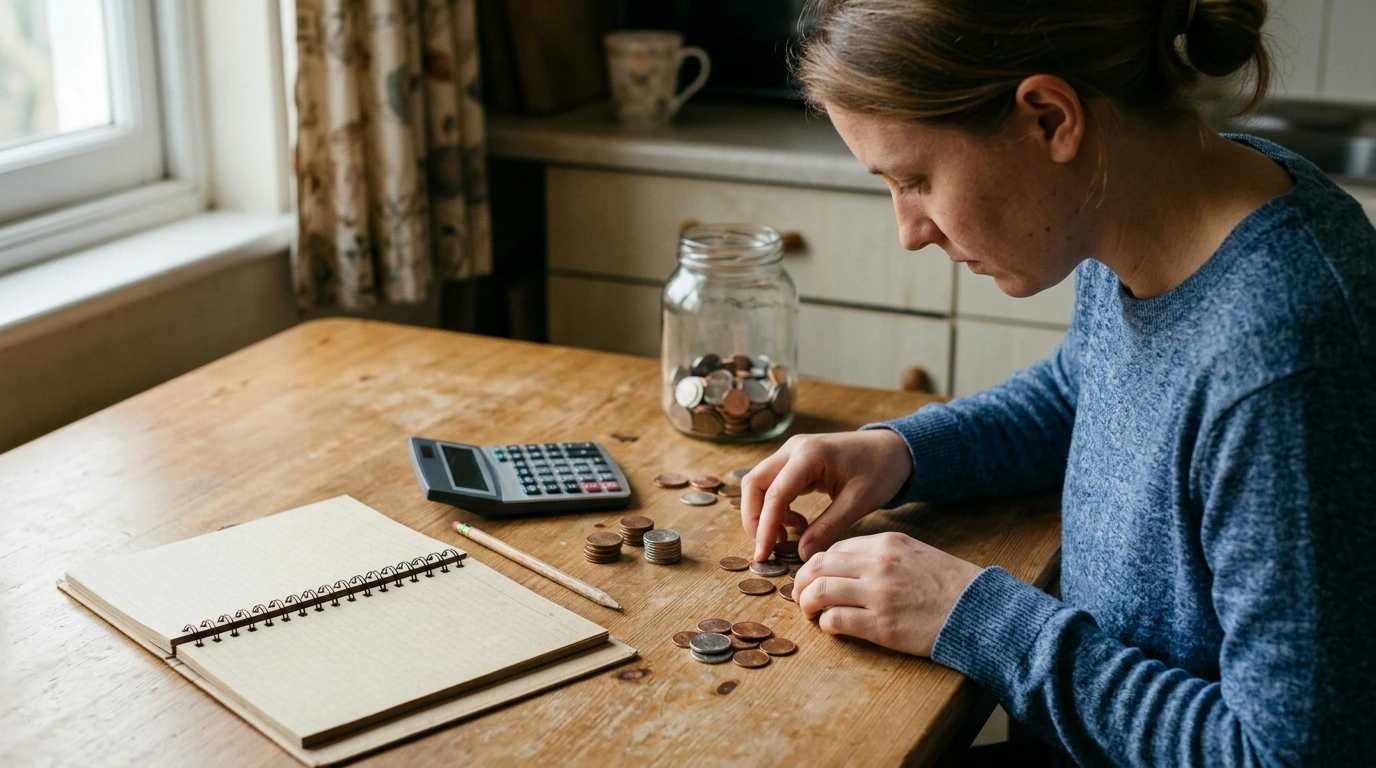
A budget is a plan for your money, not a test you pass or fail. It can help you see what is available, cover priorities and make informed choices about spending, debt and savings. When your income or expenses change, your plan can change, too.
Our Budgeting Like a Pro eBook brings several budgeting approaches together in a personal finance planner. Whether you prefer detailed categories or a broader starting framework, you can use these ideas to build a routine that fits your circumstances.
Start with a clear picture of your money
Begin with your monthly take-home income: the money you receive after taxes and other paycheck deductions. If your income varies, look at several recent months and choose a cautious estimate for planning. You can decide how to use any additional income when it arrives.
Next, list your expenses. Include recurring bills such as rent, utilities and insurance; variable costs such as groceries and transportation; and required debt payments. Review recent bank and credit card transactions to catch spending you may have forgotten, including subscriptions and small purchases.
Some costs do not arrive every month. Annual renewals, car registration and holiday gifts are easier to plan for when you estimate their yearly cost and set aside a portion each month. For example, a $120 annual renewal calls for roughly $10 a month.
Our eBook covers budgeting methods alongside debt payoff and savings planning, so you can consider these priorities together rather than treating each one as a separate task. For additional worksheets and planning tools, explore the Consumer Financial Protection Bureau’s Your Money, Your Goals toolkit.
Choose a budgeting method that fits
There is no single approach that works for every household. Start with a method that makes your choices clear, then adjust it as you learn more about your spending.
Zero-based budgeting
With zero-based budgeting, you assign every dollar of expected income a purpose. Your categories can include bills, groceries, extra debt payments and savings. The goal is for income minus planned allocations to equal zero—not for you to spend every dollar.
The 50/30/20 framework
This framework suggests dividing take-home income among needs, wants, and savings or debt repayment. The familiar starting percentages are 50%, 30% and 20%, respectively. They are guidelines, not requirements: housing costs, debt obligations and other circumstances may mean your percentages look different.
Pay yourself first
Paying yourself first means deciding on a savings contribution before allocating the rest of your income. You might arrange a transfer on payday or set aside a small amount manually. Choose an amount that still leaves room for essentials and required payments.
| Method | Starting point | Useful consideration |
|---|---|---|
| Zero-based | Assign every dollar a job | Requires regular review of categories |
| 50/30/20 | Use needs, wants and savings or debt repayment as broad categories | Percentages may need adjustment |
| Pay yourself first | Set aside savings before planning other spending | Choose an amount that leaves essentials covered |
You can combine methods, too. For example, set aside savings first, then use zero-based categories to assign the remaining income. A simple plan you revisit is more useful than a complicated one you cannot maintain.
Make room for debt payoff and savings
List each debt’s balance, interest rate and minimum payment. After accounting for essentials and required payments, decide whether an extra payment fits your budget. Even if that amount changes from month to month, writing it down gives you a deliberate starting point.
One strategy is to direct extra money toward the highest-interest balance, which can reduce interest costs over time. Another is to prioritize the smallest balance, which may provide an encouraging early milestone. With either approach, continue making required minimum payments on your other debts.
Consider building a manageable emergency cushion alongside debt repayment. A separate savings category for unexpected expenses can give you a place to start without requiring a large contribution immediately. The CFPB’s emergency savings guide offers more ideas for setting a goal and building a habit.
Put your plan into practice
Before each month begins, estimate income and assign money to your priorities. During the month, check actual spending against your plan. At the end, review what changed and adjust the next month’s categories. If an expense was higher than expected, look for a practical tradeoff instead of abandoning the budget.
For a hypothetical example, suppose you have $3,000 in monthly take-home income. You might allocate $1,900 to essentials, $300 to required and extra debt payments, $200 to savings and $600 to flexible spending. Those amounts total $3,000. Your own plan may look very different depending on your income, obligations and goals.
To put these approaches to work, our Budgeting Like a Pro: Complete eBook is in stock for $25.99. It brings budgeting, debt payoff and savings planning together in one resource. For broader everyday life-management topics, our Essential Adult Skills Guide is an optional companion.
FAQ
Can I combine zero-based budgeting with paying myself first?
Yes. Assign a savings contribution its own category first, then allocate the remaining income across expenses and other priorities.
What if the 50/30/20 percentages do not fit my expenses?
Treat the percentages as a starting guideline and adjust them to reflect your essential costs, debt obligations and savings capacity.
Should I save money while paying off debt?
A modest emergency cushion can help you prepare for unexpected expenses while repaying debt. The balance between saving and extra debt payments depends on your circumstances and obligations.

Leave a comment